
2 November 2026
Key takeaways
-
As Americans head to the polls, history offers equity investors an encouraging pattern: since 1950, US stock market performance has consistently accelerated in the year following midterm elections. Of course, correlation is not causation, and political calendars do not drive markets alone.
-
While clearing an election often relieves market uncertainty, Brazil's ballot box just delivered a jolt instead. President Lula's unexpected re-election triggered a significant repricing across Brazilian assets.
-
Chancellor Healey played it safe in his first UK Budget, pairing household energy support with a multi-year fiscal consolidation that starts reducing net debt from 2029-30. With little by way of large-scale policy announcements, the market reaction was muted. Yet sticking to the fiscal plans will be challenging.
Chart of the week – K-shaped markets
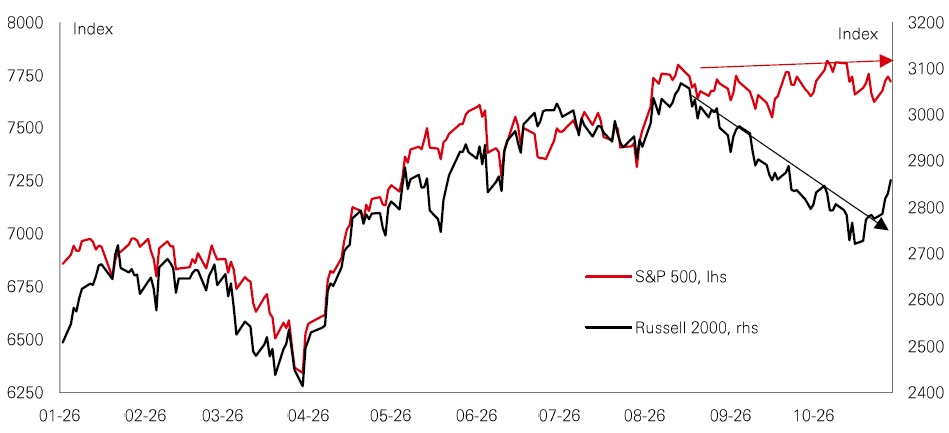
Following its October decision to leave the funds rate unchanged, the Federal Reserve faces a difficult balancing act. Restrictive policy and gradual further tightening remain necessary to bring sticky inflation back to target, especially with oil's renewed rise heightening upside inflation risks. Yet, an uneven, K-shaped economy complicates the task: policy is ultimately too accommodative for sectors benefitting directly from the AI boom, yet too tight for industries further removed from it or competing with technology companies for capital.
After moving in lockstep for much of the year, US large- and small-cap stocks have mirrored this divide, splitting into a K-shape since late summer. The S&P 500 remains buoyed by bumper mega-cap earnings, despite lingering concerns over AI capex plans. Meanwhile, the rate-sensitive Russell 2000 has fallen as markets price in more aggressive Fed tightening – current expectations of three more hikes imply a peak funds rate of over 4.50% in 2027.
However, the Fed is likely reaching the limits of how restrictive policy can become. The jump in bond yields is already doing much of the heavy lifting to cool growth, and there is a reasonable chance that oil prices moderate in line with the futures curve. A less hawkish outcome should help unwind this K-shaped divergence in markets and deliver a modest softening in the US dollar. Alongside wider AI spillovers and converging profit growth across sectors and regions, the broadening-out trade looks set to stay very much alive in 2027.
Market Spotlight
Look under the bonnet
This year’s climb in bond yields has put the “income” firmly back into fixed income, opening up compelling opportunities for investors. Yet with mainstream corporate bond spreads near the tight end of their historical range, additional value can also be found beyond the usual suspects.
Securitised credit. In simple terms, securitisation bundles pools of loans – from mortgages to corporate debt – into tradable bonds sliced into tiers, or “tranches”, letting investors choose where on the risk-and-return spectrum they want to sit. Junior tranches act like a car’s crumple zone: they absorb the impact of any loan defaults first, leaving senior AAA and single-A investors insulated while still earning attractive income. And because most of them pay floating rates, they carry near-zero duration risk, smoothing out the ride when rates are bumpy.
So why do they pay wider spreads than corporate bonds? Because intricate engineering requires skilled mechanics. Structural complexity and lower liquidity make rigorous research, security selection, and manager expertise essential, potentially rewarding investors prepared to look under the bonnet. However, these investments also carry risk.
The value of investments and any income from them can go down as well as up and investors may not get back the amount originally invested. The level of yield is not guaranteed and may rise or fall in the future. Past performance does not predict future returns. For informational purposes only and should not be construed as a recommendation to invest in the specific company, country, product, strategy, sector, or security. Diversification does not ensure a profit or protect against loss. Any views expressed were held at the time of preparation and are subject to change without notice. Any forecast, projection or target where provided is indicative only and is not guaranteed in any way. Index returns assume reinvestment of all distributions and do not reflect fees or expenses. You cannot invest directly in an index. Source: HSBC Asset Management, Factset, Bloomberg, Macrobond. Data as at 7.30am UK time 30 October 2026.
Lens on…
Capitol gains
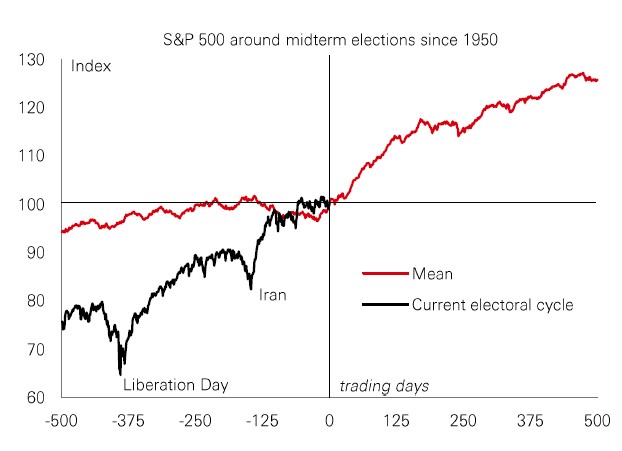
As Americans head to the polls, history offers equity investors an encouraging pattern: since 1950, US stock market performance has consistently accelerated in the year following midterm elections. Of course, correlation is not causation, and political calendars do not drive markets alone. Many post-midterm rallies coincided with powerful secular tailwinds – from 1980s disinflation and the 1990s tech surge to post-Global Financial Crisis “monetary policy on steroids” and the rise of mega-cap tech. Still, the electoral cycle plays a role. Markets dislike uncertainty, and once midterms pass, investors gain clearer visibility on the policy agenda. If the administration loses one or both chambers of Congress, it may lean more on executive actions and trade policy – yet divided government reduces the risk of sweeping fiscal or legislative surprises. |
Other volatility drivers remain, including inflation, rates, and AI. And given how strongly markets have run in recent years, another 20% gain is a tall order today. Yet after a stretch where political events – from "Liberation Day" to Iran – rattled sentiment, clearing the midterms can turn politics from a headwind into a welcome market tailwind.
A real shock
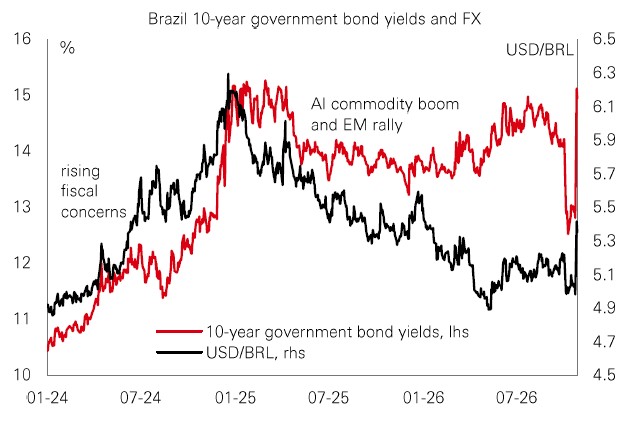
While clearing an election often relieves market uncertainty, Brazil's ballot box just delivered a jolt instead. President Lula's unexpected re-election triggered a significant repricing across Brazilian assets. Opposition gains in Congress point to legislative gridlock, complicating efforts to restore fiscal credibility and keeping Brazil's fiscal risk premium elevated. Some emerging markets debt experts think interest rates are unsustainably high and likely to move lower over the coming year, especially if pragmatic compromise with centrist lawmakers unlocks fiscal consolidation and key economic appointments calm nerves. |
However, Brazil's bigger macro story hasn’t vanished overnight. An AI-fuelled appetite for commodities and high oil prices could still play straight to the country's strengths.
Taxing times
Chancellor Healey played it safe in his first UK Budget, pairing household energy support with a multi-year fiscal consolidation that starts reducing net debt from 2029-30. With little by way of large-scale policy announcements, the market reaction was muted. Yet sticking to the fiscal plans will be challenging. Consolidation relies heavily on one lever, tax increases, despite revenues already at post-WWII highs as a percentage of GDP. Moreover, avoiding main tax rises for smaller, politically easier measures adds complexity to an already complex tax system and leaves revenues more uncertain. A greater mix of tax increases and spending cuts could reduce slippage risks, especially if cyclical deterioration knocks upwardly revised 2028-30 OBR GDP forecasts off course. |
Backloaded consolidation and persistent inflation concerns – with the BoE expected to raise rates – are likely to keep 10-year gilt yields elevated in the near term. However, G7-topping yields provide attractive income, while subdued UK growth and a possible moderation in oil prices in 2027 should ease price pressures, allowing scope for a modest decline in yields over the next 12 months.
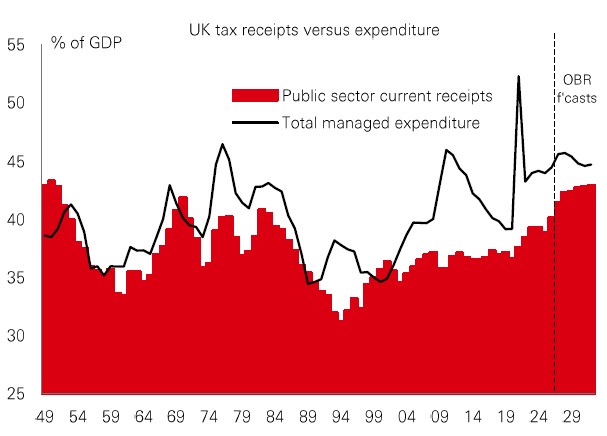
Past performance does not predict future returns. The level of yield is not guaranteed and may rise or fall in the future. For informational purposes only and should not be construed as a recommendation to invest in the specific country, product, strategy, sector, or security. Diversification does not ensure a profit or protect against loss. Any views expressed were held at the time of preparation and are subject to change without notice. Index returns assume reinvestment of all distributions and do not reflect fees or expenses. You cannot invest directly in an index. Any forecast, projection or target where provided is indicative only and is not guaranteed in any way. Source: HSBC Asset Management. Macrobond, Bloomberg, Refinitiv, FactSet. Data as at 7.30am UK time 30 October 2026.
Key Events and Data Releases
Last week

This week

For informational purposes only and should not be construed as a recommendation to invest in the specific country, product, strategy, sector or security. Any views expressed were held at the time of preparation and are subject to change without notice. Any forecast, projection or target where provided is indicative only and is not guaranteed in any way. Index returns assume reinvestment of all distributions and do not reflect fees or expenses. You cannot invest directly in an index. Source: HSBC Asset Management. Data as at 7.30am UK time 30 October 2026.
Market review
Global equities rose after recent declines, as investors assessed further corporate earnings releases and major central banks’ rate decisions. In the US, tech heavyweights were mixed, with the S&P 500 and Nasdaq higher, while the interest-rate-sensitive small-cap Russell 2000 outperformed. The Euro Stoxx 50 recovered from recent losses, alongside rallies in the DAX. In Asia, the Nikkei 225 edged higher, while the Kospi traded higher amid a week of earnings releases from semiconductor heavyweights. The Sensex advanced, while onshore mainland Chinese equities lagged their offshore counterparts. In Brazil, stock indices fell markedly following Lula’s unexpected second-round victory in the presidential election, with the Brazilian real suffering notable losses against the US dollar. Across major sovereign bond markets, US Treasury yields broadly declined. German Bund yields were largely stable, while French OAT yields fell. UK gilt yields were also down following the Autumn Budget.
Share


Related Insights


Disclaimer
This document or video is prepared by The Hongkong and Shanghai Banking Corporation Limited (‘HBAP’), 1 Queen’s Road Central, Hong Kong. HBAP is incorporated in Hong Kong and is part of the HSBC Group. This document or video is distributed and/or made available by HSBC Bank (China) Company Limited, HSBC Bank (Singapore) Limited, HSBC Bank Middle East Limited (UAE), HSBC UK Bank Plc, HSBC Bank Malaysia Berhad (198401015221 (127776-V))/HSBC Amanah Malaysia Berhad (20080100642 1 (807705-X)), HSBC Bank (Taiwan) Limited, HSBC Bank plc, Jersey Branch, HSBC Bank plc, Guernsey Branch, HSBC Bank plc in the Isle of Man, HSBC Continental Europe, Greece, The Hongkong and Shanghai Banking Corporation Limited, India (HSBC India), HSBC Bank (Vietnam) Limited, PT Bank HSBC Indonesia (HBID), HSBC Bank (Uruguay) S.A. (HSBC Uruguay is authorised and oversought by Banco Central del Uruguay), The Hongkong and Shanghai Banking Corporation Limited – Philippine Branch, HSBC Investment and Insurance Brokerage, Philippines Inc, HSBC Insurance Brokerage Company Limited, HSBC Mexico, S.A. Multiple Banking Institution HSBC Financial Group (collectively, the “Distributors”) and HSBC Bank Middle East Limited Qatar Branch, P.O. Box 57, Doha, Qatar (regulated by Qatar Central Bank for the purpose of this promotion and lead regulated by the Dubai Financial Services Authority) to their respective clients. This document or video is for general circulation and information purposes only.
The contents of this document or video may not be reproduced or further distributed to any person or entity, whether in whole or in part, for any purpose. This document or video must not be distributed in any jurisdiction where its distribution is unlawful. All non-authorised reproduction or use of this document or video will be the responsibility of the user and may lead to legal proceedings. The material contained in this document or video is for general information purposes only and does not constitute investment research or advice or a recommendation to buy or sell investments. Some of the statements contained in this document or video may be considered forward looking statements which provide current expectations or forecasts of future events. Such forward looking statements are not guarantees of future performance or events and involve risks and uncertainties. Actual results may differ materially from those described in such forward-looking statements as a result of various factors. HBAP and the Distributors do not undertake any obligation to update the forward-looking statements contained herein, or to update the reasons why actual results could differ from those projected in the forward-looking statements. This document or video has no contractual value and is not by any means intended as a solicitation, nor a recommendation for the purchase or sale of any financial instrument in any jurisdiction in which such an offer is not lawful. The views and opinions expressed are based on the HSBC Global Investment Committee at the time of preparation and are subject to change at any time. These views may not necessarily indicate HSBC Asset Management‘s current portfolios’ composition. Individual portfolios managed by HSBC Asset Management primarily reflect individual clients’ objectives, risk preferences, time horizon, and market liquidity.
The value of investments and the income from them can go down as well as up and investors may not get back the amount originally invested. Past performance contained in this document or video is not a reliable indicator of future performance whilst any forecasts, projections and simulations contained herein should not be relied upon as an indication of future results. Where overseas investments are held the rate of currency exchange may cause the value of such investments to go down as well as up. Investments in emerging markets are by their nature higher risk and potentially more volatile than those inherent in some established markets. Economies in emerging markets generally are heavily dependent upon international trade and, accordingly, have been and may continue to be affected adversely by trade barriers, exchange controls, managed adjustments in relative currency values and other protectionist measures imposed or negotiated by the countries with which they trade. These economies also have been and may continue to be affected adversely by economic conditions in the countries in which they trade. Investments are subject to market risks, read all investment related documents carefully.
This document or video provides a high-level overview of the recent economic environment and has been prepared for information purposes only. The views presented are those of HBAP and are based on HBAP’s global views and may not necessarily align with the Distributors’ local views. It has not been prepared in accordance with legal requirements designed to promote the independence of investment research and is not subject to any prohibition on dealing ahead of its dissemination. It is not intended to provide and should not be relied on for accounting, legal or tax advice. Before you make any investment decision, you may wish to consult an independent financial adviser. In the event that you choose not to seek advice from a financial adviser, you should carefully consider whether the investment product is suitable for you. You are advised to obtain appropriate professional advice where necessary.
The accuracy and/or completeness of any third-party information obtained from sources which we believe to be reliable might have not been independently verified, hence customers must seek several sources prior to making investment decisions.
The following statement is only applicable to HSBC Mexico, S.A. Multiple Banking Institution HSBC Financial Group with regard to how the publication is distributed to its customers: This publication is distributed by Wealth Insights of HSBC México, and its objective is for informational purposes only and should not be interpreted as an offer or invitation to buy or sell any security related to financial instruments, investments or other financial product. This communication is not intended to contain an exhaustive description of the considerations that may be important in making a decision to make any change and/or modification to any product, and what is contained or reflected in this report does not constitute, and is not intended to constitute, nor should it be construed as advice, investment advice or a recommendation, offer or solicitation to buy or sell any service, product, security, merchandise, currency or any other asset.
Receiving parties should not consider this document as a substitute for their own judgment. The past performance of the securities or financial instruments mentioned herein is not necessarily indicative of future results. All information, as well as prices indicated, are subject to change without prior notice; Wealth Insights of HSBC Mexico is not obliged to update or keep it current or to give any notification in the event that the information presented here undergoes any update or change. The securities and investment products described herein may not be suitable for sale in all jurisdictions or may not be suitable for some categories of investors.
The information contained in this communication is derived from a variety of sources deemed reliable; however, its accuracy or completeness cannot be guaranteed. HSBC México will not be responsible for any loss or damage of any kind that may arise from transmission errors, inaccuracies, omissions, changes in market factors or conditions, or any other circumstance beyond the control of HSBC. Different HSBC legal entities may carry out distribution of Wealth Insights internationally in accordance with local regulatory requirements.
Important Information about the Hongkong and Shanghai Banking Corporation Limited, India (“HSBC India”): HSBC India is a branch of The Hongkong and Shanghai Banking Corporation Limited. HSBC India does not distribute or refer investment products to those persons who are either the citizens or residents of United States of America (USA), Canada or any other jurisdiction where such distribution or referral would be contrary to law or regulation.
HSBC India is an AMFI-registered Mutual Fund Distributor and an AMFI-registered Specialized Investment Fund (SIF) Distributor. HSBC India distributes select mutual fund schemes and SIF strategies of empaneled Asset Management Companies, and acts as a referrer of other third-party investment products. Mutual Fund investments are subject to market risks, read all scheme-related documents carefully. AMFI-registered Mutual Fund Distributor | Date of Initial Registration: 19 Feb 2002 | ARN-0022 I Validity of ARN: 18 Feb 2027. AMFI-registered SIF Distributor I Date of initial registration: 27 Oct 2025 | ARN-0022 I Validity of ARN: 26 Oct 2028.
HSBC India will receive commission from HSBC Asset Management (India) Private Limited, in its capacity as a AMFI registered mutual fund distributor of HSBC Mutual Fund. The Sponsor of HSBC Mutual Fund is HSBC Securities and Capital Markets (India) Private Limited (HSCI), a member of the HSBC Group. Please note that HSBC India and the Sponsor being part of the HSBC Group, may give rise to real, perceived, or potential conflicts of interest. HSBC India has a policy in place to identify, prevent and manage such conflict of interest. For more information related to investments in the securities market, please visit the SEBI Investor Website: https://investor.sebi.gov.in/ and the SEBI Saa₹thi Mobile App.
The following statement is only applicable to HSBC Bank (Taiwan) Limited with regard to how the publication is distributed to its customers: HSBC Bank (Taiwan) Limited (“the Bank”) shall fulfill the fiduciary duty act as a reasonable person once in exercising offering/conducting ordinary care in offering trust services/ business. However, the Bank disclaims any guarantee on the management or operation performance of the trust business.
The following statement is only applicable to PT Bank HSBC Indonesia (“HBID”): HBID is licensed and supervised by Indonesia Financial Services Authority (“OJK”). Investment products that are offered in HBID are third party products, HBID is a selling agent for third party products such as Mutual Funds and Bonds. HBID and HSBC Group (HSBC Holdings Plc and its subsidiaries and associates company or any of its branches) do not guarantee the underlying investment, principal or return on customer’s investment. You must read and understand the investment policy of each investment product to see if a product contains ESG and sustainability elements and is classified as an ESG and sustainable investment. Investment in Mutual Funds and Bonds are not covered by the deposit insurance program of the Indonesian Deposit Insurance Corporation (“LPS”).
Important information on ESG and sustainable investing
Today we finance a number of industries that significantly contribute to greenhouse gas emissions. We have a strategy to help our customers to reduce their emissions and to reduce our own. For more information visit www.hsbc.com/sustainability.
In broad terms “ESG and sustainable investing” products include investment approaches or instruments which consider environmental, social, governance and/or other sustainability factors to varying degrees. Certain instruments we classify as sustainable may be in the process of changing to deliver sustainability outcomes. There is no guarantee that ESG and Sustainable investing products will produce returns similar to those which don’t consider these factors. ESG and Sustainable investing products may diverge from traditional market benchmarks. In addition, there is no standard definition of, or measurement criteria for, ESG and Sustainable investing or the impact of ESG and Sustainable investing products. ESG and Sustainable investing and related impact measurement criteria are (a) highly subjective and (b) may vary significantly across and within sectors.
HSBC may rely on measurement criteria devised and reported by third party providers or issuers. HSBC does not always conduct its own specific due diligence in relation to measurement criteria. There is no guarantee: (a) that the nature of the ESG / sustainability impact or measurement criteria of an investment will be aligned with any particular investor’s sustainability goals; or (b) that the stated level or target level of ESG / sustainability impact will be achieved. ESG and Sustainable investing is an evolving area and new regulations are being developed which will affect how investments can be categorised or labelled. An investment which is considered to fulfil sustainable criteria today may not meet those criteria at some point in the future.
THE CONTENTS OF THIS DOCUMENT OR VIDEO HAVE NOT BEEN REVIEWED BY ANY REGULATORY AUTHORITY IN HONG KONG OR ANY OTHER JURISDICTION. YOU ARE ADVISED TO EXERCISE CAUTION IN RELATION TO THE INVESTMENT AND THIS DOCUMENT OR VIDEO. IF YOU ARE IN DOUBT ABOUT ANY OF THE CONTENTS OF THIS DOCUMENT OR VIDEO, YOU SHOULD OBTAIN INDEPENDENT PROFESSIONAL ADVICE.
© Copyright 2026. The Hongkong and Shanghai Banking Corporation Limited, ALL RIGHTS RESERVED.
No part of this document or video may be reproduced, stored in a retrieval system, or transmitted, on any form or by any means, electronic, mechanical, photocopying, recording or otherwise, without the prior written permission of The Hongkong and Shanghai Banking Corporation Limited.